When AI Predicts Your Next Click – How Personalised Interfaces Shape Risky Decisions
AI-powered recommendation systems influence online decisions by choosing what you see, in what order and at what moment. They infer what you are likely to engage with from signals such as what you clicked, how long you lingered, when you usually open an app and what people with similar behaviour went on to do. Most of the time this simply makes services more relevant. But personalisation can raise the risk of harmful decisions when it is combined with persuasive or manipulative design in high-stakes settings, such as gambling, speculative trading or fast credit, and when systems are optimised for engagement rather than user welfare. The line between ordinary personalisation and manipulative choice architecture is not the technology itself but its effect on informed, autonomous choice. Users, researchers and regulators can evaluate these systems by asking what data shapes them, what behaviour they encourage, how transparent and reversible they are, and what independent evidence supports a platform’s claims.
AI-powered recommendation systems influence online decisions by choosing what you see, in what order and at what moment. They infer what you are likely to engage with from signals such as what you clicked, how long you lingered, when you usually open an app and what people with similar behaviour went on to do. Most of the time this simply makes services more relevant. But personalisation can raise the risk of harmful decisions when it is combined with persuasive or manipulative design in high-stakes settings, such as gambling, speculative trading or fast credit, and when systems are optimised for engagement rather than user welfare. The line between ordinary personalisation and manipulative choice architecture is not the technology itself but its effect on informed, autonomous choice. Users, researchers and regulators can evaluate these systems by asking what data shapes them, what behaviour they encourage, how transparent and reversible they are, and what independent evidence supports a platform’s claims.
A Vocabulary That Is Too Often Blurred
Public debate about “manipulative AI” often collapses very different things into a single fear, which makes it harder to identify where the real problems lie. Personalisation is simply the adaptation of content or interfaces to an individual, from showing your local weather to remembering your preferred language. Recommendation algorithms are the systems that rank and select items, such as videos, products, articles or betting markets, based on predicted relevance or engagement. Predictive analytics is broader: it uses past data to estimate the likelihood of future behaviour, such as whether a customer will churn, buy or respond to an offer. Persuasive design encourages a particular action through interface choices like prominent buttons, reminders or social proof, and is not inherently unethical: a fitness app nudging you to walk is persuasive. Dark patterns are design choices that steer users against their own interests or informed preferences, such as hidden costs, obstructed cancellation or pre-selected options. Behavioural targeting delivers messages based on inferred characteristics or behaviour. Manipulation, in its ethically meaningful sense, means exploiting cognitive or emotional vulnerabilities in ways that bypass a person’s rational agency. And demonstrated harm is something else again: evidence that a design actually caused damage to people, which is far harder to establish than the presence of a worrying mechanism.
How Personalisation Actually Works
At an accessible level, most recommendation systems run on behavioural signals: clicks, scrolls, watch time, searches, purchases, time of day, device type and sometimes location. These form an engagement history that a model uses to estimate what you might want next. Systems typically generate a pool of candidate items and then rank them, predicting the probability that you will click, watch, buy or return. Many platforms also segment users into groups with similar patterns, and some adjust recommendations to context, so that what is shown on a Friday evening on a phone may differ from what is shown on a weekday morning on a laptop. Predictive models may estimate not only what you will engage with, but whether you are likely to lapse, respond to an offer or spend more.
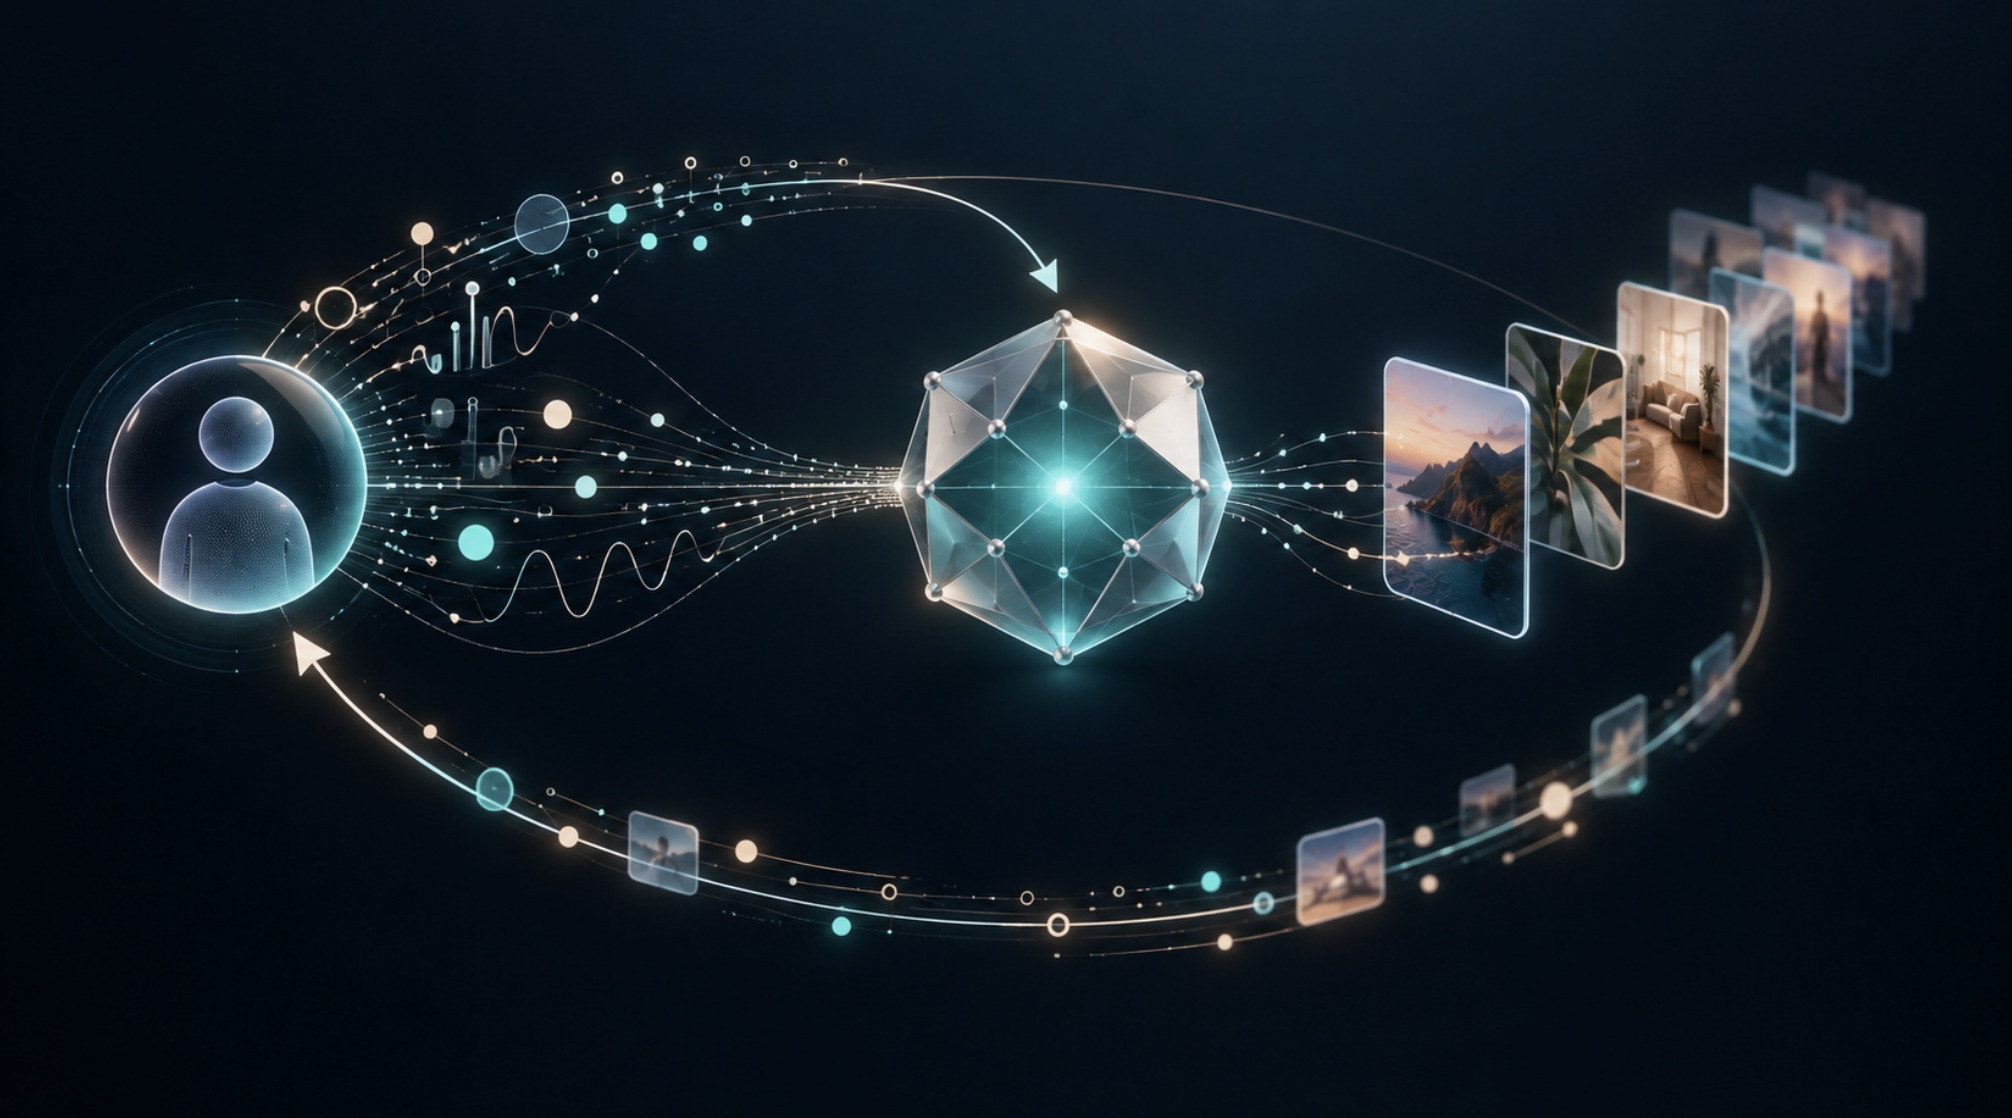
The most consequential feature is the feedback loop. Each recommendation shapes what you see, which shapes how you respond, which feeds back into the model. Over time, a system optimised to maximise a metric like engagement or revenue can narrow what you are shown towards whatever has historically kept you engaged. This happens without anyone deciding to manipulate a specific individual. Platforms differ greatly in their objectives, data, safeguards and design, and claims about “the algorithm” in general rarely apply to every system.
What an Algorithm Can Infer, and What It Cannot Know
Behavioural data can support surprisingly detailed inferences. Patterns of late-night use, rapid repeated actions, sudden increases in spending or erratic activity may correlate with fatigue, impulsivity or distress. Models can sometimes predict, at a population level, which users are likely to respond to particular prompts. These inferences are statistical, not personal understanding. An algorithm does not know why someone is awake at 2 am, whether a spending spike reflects a planned purchase or a crisis, or what the user values about their own life. It cannot reliably distinguish enjoyment from compulsion, or celebration from desperation. This gap matters ethically in both directions. A system can treat a vulnerable person’s distress signals as simply more engagement to optimise, and a well-intentioned harm-detection system can misclassify ordinary users. Either way, a prediction is a probability, not a diagnosis.
When Convenience Becomes Pressure
Helpful personalisation reduces noise: a streaming service suggests shows in a genre you like, a news app hides topics you have muted. Persuasive design goes further and encourages a specific action, such as a reminder that a series has a new episode or a highlighted “continue watching” row. Manipulative design crosses into territory where the interface undermines a person’s ability to make an informed or autonomous choice, often by exploiting predictable biases at the moments they are most influential.
The same building blocks appear across all three categories. Default settings that turn on notifications or auto-renewals shape behaviour because many people never change them. Frictionless transactions, such as one-tap payments and saved cards, remove the pause in which people reconsider. Urgency cues like countdown timers or “only today” offers compress decision time. Repeated prompts can wear down resistance. Variable rewards, whose timing or size is unpredictable, can make activities feel more compelling. Personalised notifications arrive when a model predicts you are most likely to respond. Loss framing (“don’t miss out”, “you’re about to lose your streak”) leans on loss aversion. And selective information display can make benefits prominent while costs, odds or risks are relegated to small print or extra screens.
Consider two hypothetical examples. A music app learns that a listener enjoys new jazz releases on Sunday mornings and surfaces them then. That is helpful personalisation with little downside. A different app learns that a user is most likely to make a purchase late at night after a run of losses in a game, and sends a discounted bundle offer at that moment with a countdown timer. The mechanisms are similar; the ethical implications are not.
Why High-Risk Contexts Deserve Extra Scrutiny
Online gambling, retail trading apps, high-cost consumer credit, compulsive shopping and in-app purchasing all involve money, uncertainty and the possibility of rapid escalation. They are not identical. Gambling products are typically designed so that, over time, the operator retains a margin from players, and outcomes are largely or entirely determined by chance. Trading apps involve real assets whose prices can rise or fall, where gamified interfaces may encourage frequent trading even though active trading carries risk for retail investors. High-cost credit, including buy-now-pay-later and small loans, can turn small decisions into growing debt. In-app purchases range from harmless cosmetic items to loot-box-style mechanics that some researchers have linked to problem-gambling symptoms, although the direction of causation remains debated. Compulsive shopping is driven by a complex mix of individual factors and marketing. Engagement in any of these is not equivalent to addiction, and most users do not experience harm. But where harms do occur, they can be severe, and design choices that would be trivial in a recipe app carry very different weight in these settings.
A Hypothetical Gambling Case Study
The following scenario is fictional and describes possible mechanisms, not documented features of any platform.
Imagine an adult who uses an online wagering app mainly on weekends. After a few months, their activity becomes more frequent and moves later into the night. A highly personalised interface might respond in several ways. Recommendations might prioritise fast-resolving markets or games that this user previously engaged with longest, which would make sessions feel continuous. Notifications might arrive at times the model associates with high engagement, such as just after payday. Balance and spending information might be visible but less prominent than promotional content, which could reduce awareness of total losses. Safer-gambling messages might be shown in standard positions that the user has learnt to ignore, and stopping or closing the account might require more steps than depositing.
Each of these mechanisms is plausible, and some are discussed in research on gambling design and dark patterns. Plausibility is not proof, however. Without access to the platform’s data, outcomes and experiments, it is impossible to say whether such design actually caused the user to gamble more, or whether the change reflected life circumstances, existing vulnerability or choices that would have occurred anyway. Responsible analysis keeps these questions separate.
The Research Problem: Studying Systems We Cannot See
Much of the evidence about manipulative design comes from interface audits, laboratory experiments and surveys. A widely cited 2019 study by Arunesh Mathur and colleagues used automated crawling of around 11,000 shopping websites and found dark patterns on a meaningful minority of them, many of which could be classed as deceptive. Studies of recommendation systems often rely on simulations, sock-puppet accounts or data donated by users, because platforms rarely share internal models, ranking objectives or experiment results. Correlation is also a persistent challenge. If heavy users of a feature report more harm, that may mean the feature contributes to harm, or that people already experiencing harm use the feature more. Proprietary A/B testing inside companies can identify causal effects precisely, but those results are seldom published. This asymmetry is why many regulators are moving towards transparency obligations, data access for researchers and independent audits, rather than relying on industry assurances.
The Regulatory Picture in 2025 and 2026
Internationally, the European Union’s Digital Services Act requires online platforms to explain the main parameters of their recommender systems. The largest platforms must offer at least one recommendation option not based on profiling. The EU’s AI Act prohibits certain AI practices that deploy manipulative or deceptive techniques to materially distort behaviour in ways likely to cause significant harm, with those prohibitions applying since February 2025. These rules do not apply directly in Australia, but they shape global platform design and local debate.
In Australia, the Australian Consumer Law (ACL), enforced by the ACCC, prohibits misleading or deceptive conduct and unconscionable conduct. It does not currently contain a general prohibition on “unfair trading practices” of the kind found in some other jurisdictions. The federal government has consulted on introducing one, and readers should check the current status of that reform. The ACCC’s multi-year Digital Platform Services Inquiry, which concluded in 2025, repeatedly examined dark patterns, data practices and consumer harms on digital platforms.
On privacy, the Privacy and Other Legislation Amendment Act 2024 introduced reforms including a statutory tort for serious invasions of privacy. It also introduced new transparency requirements for organisations that use personal information in substantially automated decisions that significantly affect individuals, which are scheduled to commence in December 2026. The Office of the Australian Information Commissioner (OAIC) is also developing a Children’s Online Privacy Code. These measures are relevant to profiling, but they do not specifically regulate recommendation systems in gambling.
Gambling-specific rules sit alongside this general framework. The Interactive Gambling Act 2001 restricts which online gambling services can be offered to Australians. Licensed online wagering providers must participate in BetStop, the national self-exclusion register launched in 2023, and since June 2024 they have been banned from accepting credit cards. The National Consumer Protection Framework for online wagering sets additional requirements, such as activity statements and deposit limits. Gambling advertising remains contested. A 2023 parliamentary committee report recommended a phased, comprehensive ban, and debate about how far restrictions should go continues. The distinction matters: general consumer and privacy law asks whether conduct is misleading, unconscionable or unlawful with data, while gambling regulation imposes product- and sector-specific obligations.
Six Questions to Ask About a Personalised Interface
The following framework is intended for users, researchers and regulators alike.
1. What data shapes the experience? Is personalisation based on explicit preferences, on observed behaviour or on inferred characteristics such as vulnerability or spending potential?
2. What behaviour is the interface encouraging? More time, more spending, more frequent returns, or task completion and satisfaction?
3. Can the user understand why content is shown? Are there explanations, controls or non-personalised alternatives?
4. How easy is it to pause, refuse or disengage? Compare the steps to stop, limit or cancel with the steps to continue or spend.
5. Are costs and risks visible before action? Are prices, odds, losses, fees or time spent clearly displayed at the moment of decision?
6. What independent evidence supports the platform’s claims? Are there audits, published research, regulatory findings or verifiable safety data, or only marketing statements?
Applying the framework to two cases
Take a hypothetical streaming service that recommends documentaries based on viewing history. It uses explicit and behavioural signals, encourages watching more content, offers a simple “because you watched” explanation, and lets users turn off autoplay. The cost is a fixed subscription, and the risks are relatively modest: lost time rather than escalating losses. Autoplay deserves scrutiny, but the overall stakes are lower.
Now take a hypothetical wagering app using similar recommendation techniques. The same autoplay-like continuity, such as instantly suggesting the next race or event, operates where each action costs money and outcomes are uncertain. If recommendations rely on signals associated with impulsive play, if stopping is harder than continuing, and if losses are less visible than offers, the identical design pattern raises very different ethical concerns. Context changes the ethics, even when the code looks similar.
Evaluating Gambling Interfaces Without Assumptions
These questions also apply when people encounter gambling brands online. Someone who sees a branded search phrase such as Westio casino site, or the name of any other operator, learns nothing from the name alone about whether that platform uses AI personalisation, how its recommendations work, which behavioural techniques it uses or what safeguards are in place. Those are properties of the system and of the regulatory framework it operates under, and they can only be assessed through observation, disclosures, regulatory information and independent evidence. Assuming either good or bad practice from a brand name is guesswork.
What Users and Regulators Can Do
For individual users, practical steps include reviewing notification settings, removing saved payment methods from apps that encourage spending, using available activity statements and limits, and checking whether services offer non-personalised feeds. In Australia, people concerned about gambling can use BetStop for licensed online wagering, bank gambling blocks where available, and support from the National Gambling Helpline. For researchers, the priorities are access to platform data under appropriate safeguards, methods that separate correlation from causation, and attention to outcomes rather than mechanisms alone. For regulators, the trend internationally is towards transparency of recommender systems, limits on manipulative design, and testing obligations in high-risk sectors. These tools are being discussed, and to varying degrees adopted, across jurisdictions.
Personalisation With a Purpose
Personalisation is neither inherently benign nor inherently sinister. It becomes ethically significant when the system’s goals diverge from the user’s interests and when the stakes involve money, health or time that cannot be recovered. As AI systems become better at predicting the next click, the more important question is whether they help people make the choices they would endorse on reflection. Answering that requires transparency, independent evidence and attention to context, not just better algorithms.